News
Erryn Barkett: Why Growing Assets Call for Regularly Updated Insurance Coverage

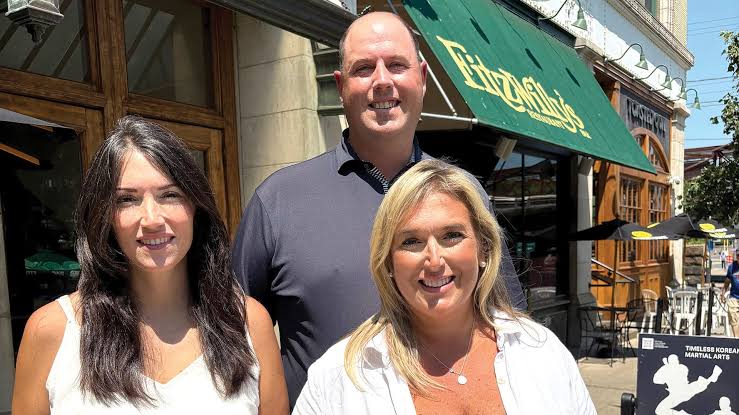
Erryn Barkett is a Virginia-based entrepreneur and the founder and CEO of C4T, LLC, where he has spent more than 25 years guiding clients through wealth management, portfolio allocation, and succession planning. Erryn Barkett also leads SkyPix, LLC, an aerial photography company, drawing on his credentials as a certificated flight instructor and commercial multi-engine pilot with more than 6,000 flight hours. His entrepreneurial background spans restaurants, farming, real estate, and aviation, giving him firsthand experience with how different types of assets create distinct coverage needs. That range of ventures illustrates why insurance reviews become more complex as an owner’s holdings expand across personal, business, and specialized categories such as agricultural or aviation-related activity.
A person may begin with one home or one business interest and later add rental property, business equipment, crops, livestock, or aircraft-related activity. Each addition can make old coverage assumptions less reliable.
Insurance needs include the losses a policy should address and the people, property, or activities it should protect. The issue is not only the value of what the owner holds, but also whether each asset creates different property, liability, or operating concerns.
A useful review starts by identifying what the owner owns before assuming existing policies answer every situation.
That means asking what damage each asset could suffer, who could make a claim, and which event would trigger coverage. The answer can change when an asset moves from personal use into rental, business, agricultural, or aviation-related use.
That first inventory often separates personal property from business property. A couch in a living room does not require the same records as machinery, inventory, or tools a business uses.
Business assets may need records showing how the owner acquired them, what they cost, what improvements the owner made, and when the owner sold or removed them from service.
Real estate adds another layer when someone else occupies the property. A home the owner uses personally differs from a property the owner rents to tenants, paying guests, or short-term visitors.
Rental use can introduce questions about guest injuries, property damage, liability coverage, and whether the policy reflects who occupies the property and how they use it.
From there, an operating business changes the review from property ownership to daily activity. A restaurant depends on equipment, inventory, furniture, deliveries, staffing, and customer traffic.
Those conditions create liability and property questions that differ from owning a building that does not host active operations. Some business losses matter because operations stop, not only because property damage occurs.
If a restaurant, store, or service business cannot operate normally after an event the policy covers, the owner may still owe rent, payroll, loan payments, taxes, and other fixed costs.
That makes lost income and continuing expenses a separate review point from repair costs.
Farm and livestock ownership bring the review into agricultural production. Crop insurance works as a risk management tool for agricultural producers, and available policies can depend on the crop, county, state, commodity, and policy terms that apply.
Livestock programs also show why cattle or dairy exposure may require a different review from a standard home, rental, or storefront example.
Aircraft-related activity deserves separate attention because aviation carries specialized ownership and liability questions. Aircraft registration depends on legal ownership.
Renters insurance questions may involve aircraft-damage protection, liability limits, per-passenger limits, defense costs, pilot qualifications, recent experience, and the aircraft types the pilot flies.
Rented aircraft, flight school, flying club, or aircraft-owner requirements can raise questions that ordinary property or business equipment coverage does not answer.
Across these categories, records serve as evidence of the asset picture. The owner needs information about purchase dates, legal ownership, values, locations, financing, improvements, repairs, and disposal.
Those details help show what exists, where it is, and whether the asset belongs to a personal, rental, business, agricultural, or aviation-related activity.
Insurance review works best before a new asset creates a claim, cost, or responsibility the owner has not clearly accounted for. When ownership expands, the owner should review policy language, limits, records, and possible claims while changes are still fresh.
That timing can help the owner correct gaps early instead of discovering them only after a loss.
About Erryn Barkett
Erryn Barkett is a Virginia-based entrepreneur who founded and leads C4T, LLC, a wealth management firm, as well as SkyPix, LLC, an aviation-based aerial photography company. He holds a bachelor’s degree in psychology from the University of Richmond and is a certificated flight instructor and commercial multi-engine pilot with more than 6,000 flight hours. Over more than 25 years, Erryn Barkett has built an entrepreneurial career spanning real estate, agriculture, hospitality, and aviation.

Hiring Trends in Chennai: Investment Banking + Financial Analytics Skills Are Winning in 2026

Erryn Barkett: Why Growing Assets Call for Regularly Updated Insurance Coverage

Inside the Multi-Million Dollar Gaming Economy: How Streamers and Digital Assets Drive the Virtual Currency Boom

Find the Right T-Shirt for Every Vibe

Building Sustainable Rental Success With Professional San Antonio Property Management

Cove Lighting and False Ceilings: Creating a Soft, Layered Glow

How Everyday Patients Choose Between Cosmetic Upgrades and Tooth Replacement

A Realistic Guide to Restoring Chipped, Missing, or Worn Teeth

Safer Aging at Home: A Daily Plan for Mobility, Fall Prevention, and Peace of Mind

Teeth Whitening Options: What Actually Works

BPC-157 UK: A Research-Focused Guide to the Experimental Peptide

Online Gaming and Comedy Gold: Kevin Hart Takes to the (Digital) Stage

Mexico City museums, parks and food markets: a culture-first itinerary

Top 6 AI Document Processing Platforms for Enterprise Workflow Automation

ADA Signage: What Every Business Should Know About Interior Signs

How Trauma Therapy Works: Methods, Timelines & What to Expect

Don Toliver Net Worth: Height, Age, Real Name, Career & More
Don Toliver is an American rapper and singer best known for his RIAA platinum certified songs, No Idea and After...

Finesse2tymes Net Worth: Height, Age, Real Name & Career
Finesse2tymes is an American rapper and recording artist. He is mainly recognized for his thunderous voice and motivational lyrics in...

Sugarhill Ddot Net Worth: Height, Age, Real Name & Career
Sugarhill Ddot is an American hip-hop recording artist best known for his songs, Real Facts and I Wanna Love You....

GloRilla Net Worth: Height, Age, Bio, Real Name & Career
GloRilla is an American rapper and hip-hop recording artist from Memphis. She is best known for her popular singles, “Westside...

Destroy Lonely Net Worth: Height, Age, Real Name & Career
Destroy Lonely is an American rapper best known for his 2022 mixtape, No Stylist. He is currently signed to rapper...
-
Rappers2 years ago
GloRilla Net Worth: Height, Age, Bio, Real Name & Career
-
 News2 years ago
Trash To Treasure: Maximizing Space And Efficiency Through Junk Removal
-

 Businessman3 years ago
7 Proven Lead Generation Strategies To Implement in 2023
-
 Businessman2 years ago
Brandon Fugal Net Worth: How Rich is Skinwalker Ranch Owner?
-

 Rappers3 years ago
BigXthaPlug Net Worth: Height, Age, Real Name & Career
-

 TV Stars2 years ago
Kaleb Cooper Net Worth: How Rich is the TV Star Actually?
-
 Internet Stars4 years ago
Mufti Menk Net Worth: How Rich is the Islamic Speaker Actually?
-
 TV Stars2 years ago
Carla Diab Net Worth: How Rich is the TV Star Actually in 2025?
You must be logged in to post a comment Login