Articles
Hurt at Work? A Second Claim Might Cover Pain Comp Ignores

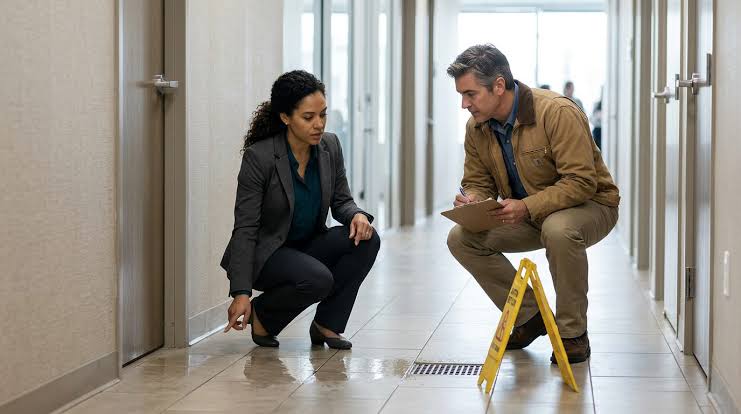
Danny was three stops into his morning delivery route when a pickup truck ran a red light and crushed the side of his van. Within a week he had a claim number, a company doctor, and a pile of forms. Nobody told him that strong legal representation for workplace injuries often starts with one simple question about who else caused the crash.
That question matters more than most injured workers realize. Workers’ compensation covers a lot, but it was never built to cover everything. For many people, the bigger recovery sits in a separate claim they never hear about.
Job injuries are hardly rare. Injury and illness data from the Bureau of Labor Statistics counts more than two million cases each year in private industry alone. Behind every number is a person juggling medical bills, missed paychecks, and a body that refuses to cooperate.
A Deal Struck Long Before Anyone Got Hurt
Comp works like a trade. Workers get benefits without proving that anyone was careless. In return, they usually give up the right to sue their employer.
That bargain has real upsides. A worker who slipped on a wet floor, or simply lifted a box the wrong way, can still collect. Fault rarely enters the picture.
But the trade carries a price. Benefits follow formulas written into law. Nobody asks how much the injury changed someone’s daily life. The system asks which body part was hurt, how badly, and for how many weeks.
Employers often pick the treating doctor, at least at first. That doctor’s notes shape nearly every decision that follows, so describing symptoms honestly and completely at each visit matters.
Where Comp Comes Up Short
Most comp programs replace only part of lost wages, often around two-thirds, and many cap weekly checks. Medical care is covered, but usually through approved doctors and strict treatment guidelines.
Then comes the gap that surprises people most. Comp generally pays nothing for pain and suffering. It offers nothing to a spouse for lost companionship. It does not punish a reckless company.
Picture two workers with identical back injuries. One collects comp alone. The other also files against the careless driver who caused the wreck. Months later, their recoveries can look wildly different.
Meet the Third Party
A third party is anyone at fault who is not the employer. That group is wider than most people assume. Common examples include:
- A distracted driver who slams into a work vehicle
- A manufacturer that built or sold faulty equipment
- A subcontractor whose crew left a hazard on a shared site
- A property owner who ignored a broken railing or loose stairs
- A maintenance firm that skipped a required inspection
A claim against one of these parties follows ordinary negligence rules. Full lost earnings, reduced future earning power, and pain and suffering can all come into play.
Money Flows Back, but Not All of It
There is a catch worth knowing. When a third party claim pays out, the comp insurer usually wants repayment for what it already covered. Lawyers call this a lien, or subrogation.
Rules on that repayment differ from place to place. Some laws cap the insurer’s share or require it to help pay legal costs. A sharp attorney reads those rules closely, because the split can shift thousands of dollars.
Even after a lien, workers often walk away with far more than comp alone would provide.
Timing matters here too. Some insurers push to resolve the lien early, before the injured worker fully understands the numbers. Patience and a careful review usually pay off.
Deadlines Move Faster Than Healing
Most systems set a short window to report an injury to an employer, often 30 days or less. Filing the formal claim carries a separate deadline. Appeals after a denial can be tighter still, sometimes measured in days.
Third party lawsuits run on their own clock, which is usually longer but still firm. Miss it and the claim disappears, regardless of its strength.
Recovery takes months. Deadlines do not wait for it.
Small Moves That Protect a Claim
Report the injury in writing and keep a copy. Snap photos of the scene, the equipment, and any visible injuries. Write down the names of coworkers and anyone else who saw what happened.
Be careful with recorded statements. Adjusters sometimes use early answers to argue that a condition existed before the accident.
Retaliation is another concern. Firing someone for filing a valid comp claim is illegal in most places. Employees who report unsafe conditions also have whistleblower protections through OSHA, though complaint windows can be short.
Above all, avoid settling the comp claim before someone checks for a third party. A comp settlement can sometimes affect the other case.
Keep a simple journal as well. Note pain levels, sleepless nights, missed family events, and chores that suddenly feel impossible. Those details bring a third party claim to life.
Frequently Asked Questions
Can someone sue an employer after a workplace injury?
Usually not. Comp is typically the exclusive remedy against an employer. Narrow exceptions may apply, such as an employer that skipped required coverage or caused harm on purpose.
Does a worker need to be blameless to collect comp?
No. Comp is a no-fault system, so carelessness rarely blocks benefits. Intoxication or horseplay can be exceptions in many places.
Can a comp claim and a third party claim happen at once?
Yes. They often run side by side. The comp claim handles immediate needs while the negligence case builds.
Do independent contractors qualify for comp?
It depends on the actual working relationship, not just a job title or tax form. Many workers labeled as contractors turn out to be employees under the law.
How long does a third party case usually take?
Timelines vary widely. A simple car crash claim may settle within months, while a defective machine case can stretch for years. Medical recovery often sets the pace, since a fair settlement depends on knowing the full extent of the harm.
One Question Worth Asking Early
Danny’s case turned on a single detail. Someone outside his company caused the crash. That fact opened a second door that comp alone never would have.
Every work injury deserves the same look. Ask who else played a part, whether a driver, a manufacturer, a contractor, or a landlord. The answer can change what recovery looks like.

Top SEO Agencies for Automotive Brands in Australia

Hurt at Work? A Second Claim Might Cover Pain Comp Ignores

How to Create Trustworthy Product Images That Help Shoppers Buy With Confidence

Game Music and Sound Design: How Audio Shapes Online Play

Biggest CFD Brokers in the World: Who Leads the Global Market?

Your First Gum Measurements: Making Sense Of The Numbers

Biltema Tools, Car and Garden Products: A Practical Owner’s Guide to Using Product Manuals

A Look at the UK’s Online Gaming Landscape

Mexico City museums, parks and food markets: a culture-first itinerary

How an Edit Stays Useful After the Face Paste Stops Impressing Anyone

ADA Signage: What Every Business Should Know About Interior Signs

Understanding Single-Account Gaming Platforms and Their Benefits

Cove Lighting and False Ceilings: Creating a Soft, Layered Glow

Where to Find Pennsylvania’s Best Pizza During National Pizza Month

Corporate Gifts for Better Business Brand Promotion Now

Inside the Multi-Million Dollar Gaming Economy: How Streamers and Digital Assets Drive the Virtual Currency Boom

Don Toliver Net Worth: Height, Age, Real Name, Career & More
Don Toliver is an American rapper and singer best known for his RIAA platinum certified songs, No Idea and After...

Finesse2tymes Net Worth: Height, Age, Real Name & Career
Finesse2tymes is an American rapper and recording artist. He is mainly recognized for his thunderous voice and motivational lyrics in...

Sugarhill Ddot Net Worth: Height, Age, Real Name & Career
Sugarhill Ddot is an American hip-hop recording artist best known for his songs, Real Facts and I Wanna Love You....

GloRilla Net Worth: Height, Age, Bio, Real Name & Career
GloRilla is an American rapper and hip-hop recording artist from Memphis. She is best known for her popular singles, “Westside...

Destroy Lonely Net Worth: Height, Age, Real Name & Career
Destroy Lonely is an American rapper best known for his 2022 mixtape, No Stylist. He is currently signed to rapper...
-
Rappers2 years ago
GloRilla Net Worth: Height, Age, Bio, Real Name & Career
-
 News2 years ago
Trash To Treasure: Maximizing Space And Efficiency Through Junk Removal
-

 Businessman3 years ago
7 Proven Lead Generation Strategies To Implement in 2023
-
 Businessman2 years ago
Brandon Fugal Net Worth: How Rich is Skinwalker Ranch Owner?
-

 Rappers4 years ago
BigXthaPlug Net Worth: Height, Age, Real Name & Career
-

 TV Stars2 years ago
Kaleb Cooper Net Worth: How Rich is the TV Star Actually?
-
 Internet Stars4 years ago
Mufti Menk Net Worth: How Rich is the Islamic Speaker Actually?
-
 TV Stars2 years ago
Carla Diab Net Worth: How Rich is the TV Star Actually in 2025?
You must be logged in to post a comment Login